Jupiter · Cost of Living
Cost of Living in Jupiter, Florida
A listing price and an old tax bill do not add up to an ownership budget. How to build the real number for one Jupiter address, line by line, from current quotes and public records.
By John OliverUpdated

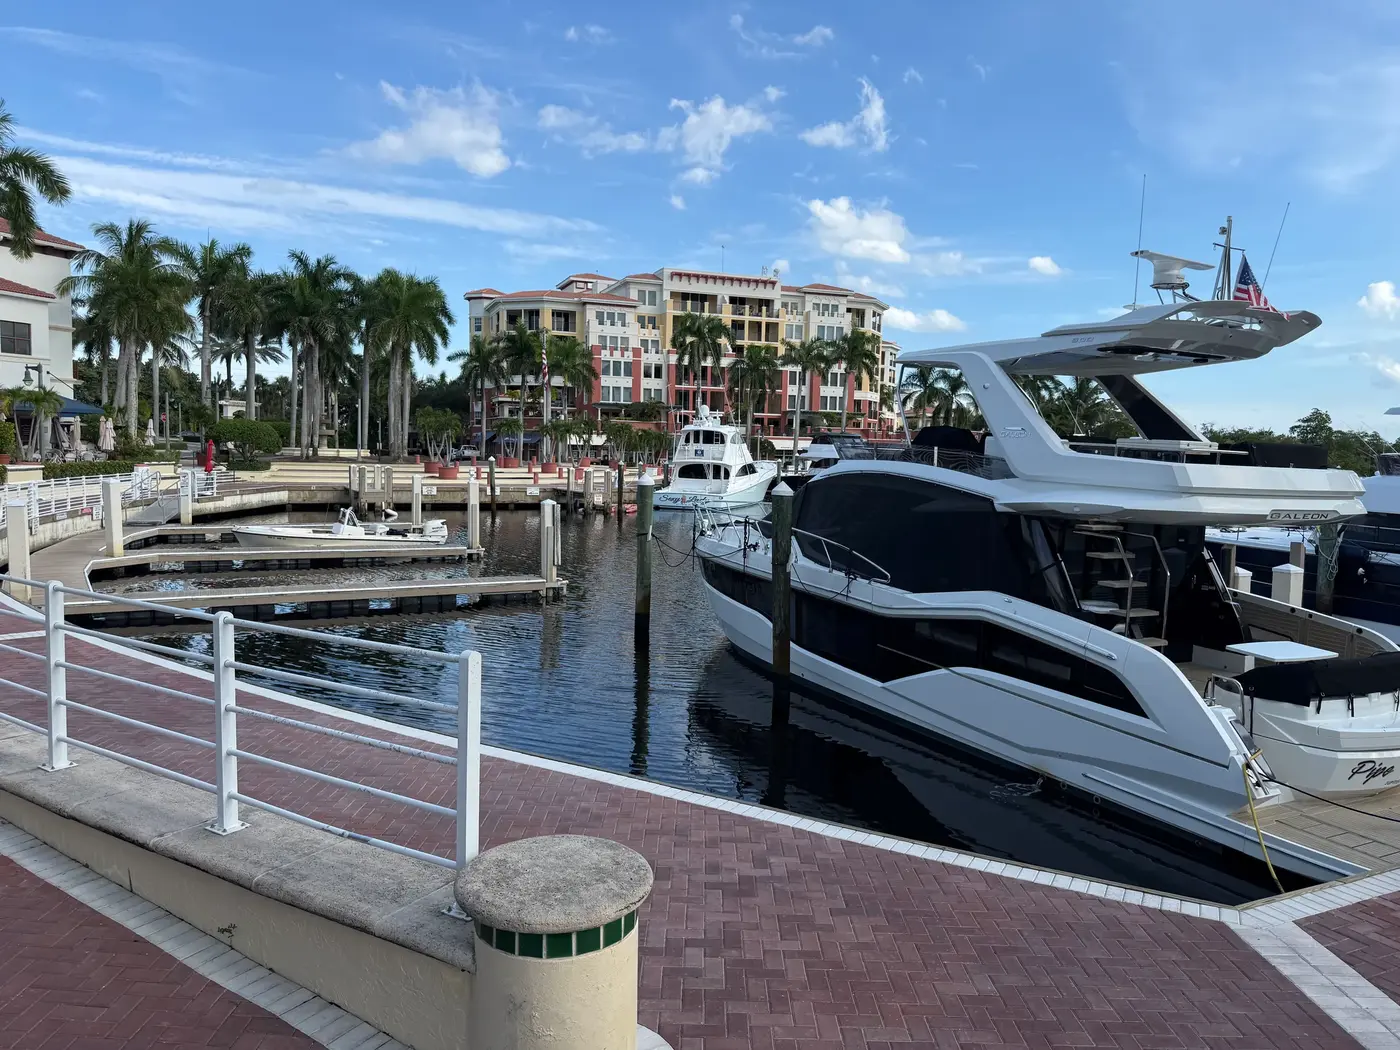
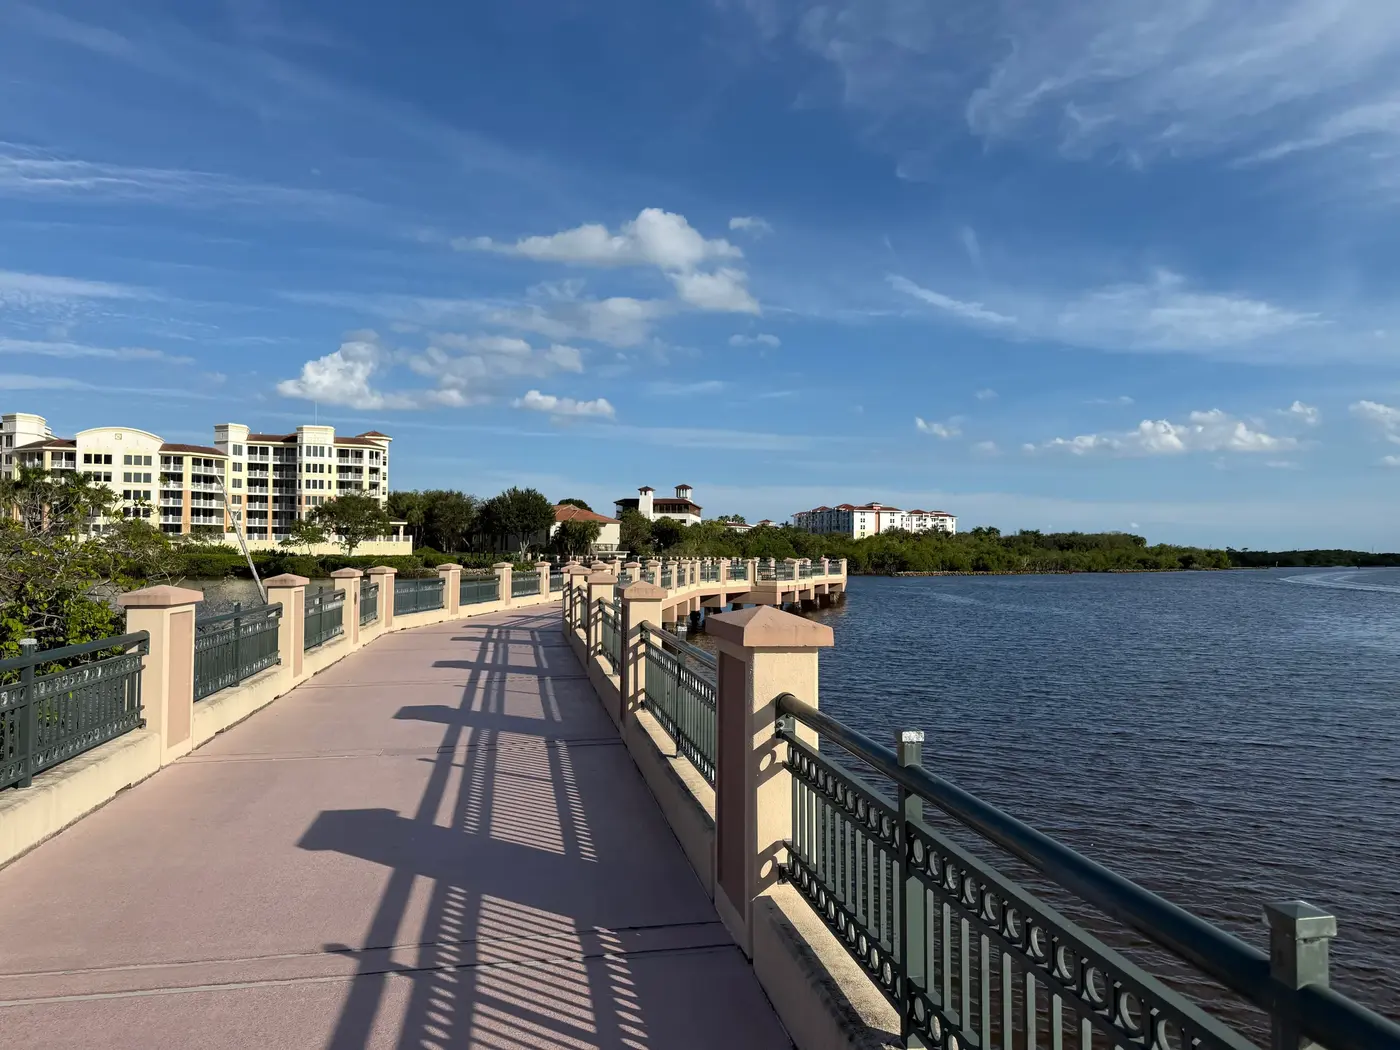
Condominium buildings across the water from the Jupiter Riverwalk. One of several housing contexts in the Jupiter mailing area.
The useful question is not what Jupiter costs. It is what one specific address costs to own. A listing price tells you the purchase; the seller's old tax bill tells you what the seller paid; neither one is your budget. The same Jupiter mailing address can lead to very different ownership costs depending on which jurisdiction the parcel is in, the property type, the association and any club attached to it, waterfront exposure, the building's condition, the roof and systems, the insurance quotes those produce, and how water, sewer and power reach the house.
This guide is a method, not a set of numbers. Every section says what to pull for the property you are considering and where the official source is. Nothing here is tax, insurance, legal, lending or investment advice; the licensed professionals named along the way are. For how the area is organized, read the neighborhood guide; for the trade-offs, read the pros and cons.
In this guide
Housing: categories, not price promises
Jupiter's housing comes in several contexts, and each carries its own diligence. What follows is what may matter for each, not which costs more and not who buys it.
- Condominium or townhouse. The association's budget, reserves, assessments and rules shape the monthly figure as much as the mortgage does. Insurance responsibility is split between the association's policy and yours, and the split is in the documents.
- Inland single-family home. The roof, the openings, the systems and any association come first. Some have no association at all; some have one with limited scope.
- Association or club community. Dues and what they include, any mandatory club membership with its own joining cost and dues, and the rules that govern rentals, exterior changes and vehicles.
- Waterfront, river, inlet, canal or marina-adjacent property. Everything above, plus the seawall, dock and lift, their permits, the depth and clearances on the route a boat would take, and what legally conveys with the deed.
- Acreage-style or unincorporated-area property. Jurisdiction, well and septic where they apply, and the maintenance a larger lot carries.
The live market trends further down this page come from the local MLS and show current list-market conditions. They are not a substitute for a property-specific budget, and this page does not quote a median for the same reason: the spread inside Jupiter is wider than any single figure.
Property taxes: use the calculator, not the listing
A listing's prior tax bill reflects that parcel's current assessment and whatever exemptions its current owner holds. It may not predict a future owner's bill.
The Palm Beach County Property Appraiser publishes a property tax calculator for exactly this. Search for the property, open the calculator from its record, enter the price you are contemplating and whether you intend to homestead it, and it returns an estimate built on current millage. Run it before you write an offer. The Appraiser's residential appraisal page explains how residential property is valued.
Three terms you will meet, each eligibility-based:
- Homestead exemption. An owner who makes the property a permanent residence may be eligible for an exemption that reduces its taxable value. The Florida Department of Revenue's exemptions overview describes it, and the application deadline is March 1.
- Save Our Homes. After a homestead is established, annual increases in the assessed value are limited by Florida law. It applies to eligible homestead property, and it begins with your ownership, not the seller's.
- Portability. An eligible owner moving from one Florida homestead to another may be able to transfer some or all of the accumulated assessment difference, within the time limits the Department of Revenue sets out in its portability guidance.
Whether any of these applies to you, by how much, and on what timeline is a question for the Property Appraiser and a qualified tax professional. This page predicts no savings.
Insurance, flood and mitigation: a document checklist
Insurance pricing and availability are set by insurers for one property at a time. Instead of generalizing, gather the documents that let an insurer and a licensed agent quote the exact house:
- A written homeowners quote for the exact property, obtained during the inspection period.
- A flood quote, and a review of whether coverage is required or appropriate. Flood coverage is generally a separate policy from a standard homeowners policy. Whether a lender requires it, and whether it suits the property, depends on the property, the lender, the policy and professional advice. Look the parcel up at the FEMA Map Service Center.
- Roof age, condition, permits and maintenance records.
- Wind-mitigation documentation where it exists. Qualifying features may affect the discounts an insurer offers. Citizens Property Insurance's inspections page describes the wind-mitigation inspection and notes that one is generally valid for up to five years if the structure has not materially changed.
- Four-point inspection requirements as set by the insurer you select. The same Citizens page describes its own requirement for older homes; other carriers set their own.
- Flood zone, elevation and evacuation information. The Town's flood, evacuation and insurance page is the local starting point.
- Deductibles, exclusions and coverage limits, reviewed with a licensed insurance professional.
No carrier, approval, coverage amount or premium is promised here. The quote for the house is the only number that counts.
Association, condominium, club and CDD obligations
Read before you offer. These are the documents that turn "the dues" into a real monthly figure:
- The current association or condominium budget and fee schedule.
- What the dues include and exclude, line by line.
- Reserve funding, and any current or pending assessments.
- Insurance responsibility and how deductibles are allocated between the association and the owner.
- Rules on rentals, pets, parking, exterior changes, docks, boats and generators.
- Club obligations, only where the community's own documents identify them: whether membership is mandatory, what it costs to join and keep, and what happens on resale.
- Any Community Development District assessment, only where it appears on the parcel's tax record.
Not every Jupiter community has a club or a district, and the documents for the one you are considering are the only ones that count. Questions about what an association is required to do are for an attorney.
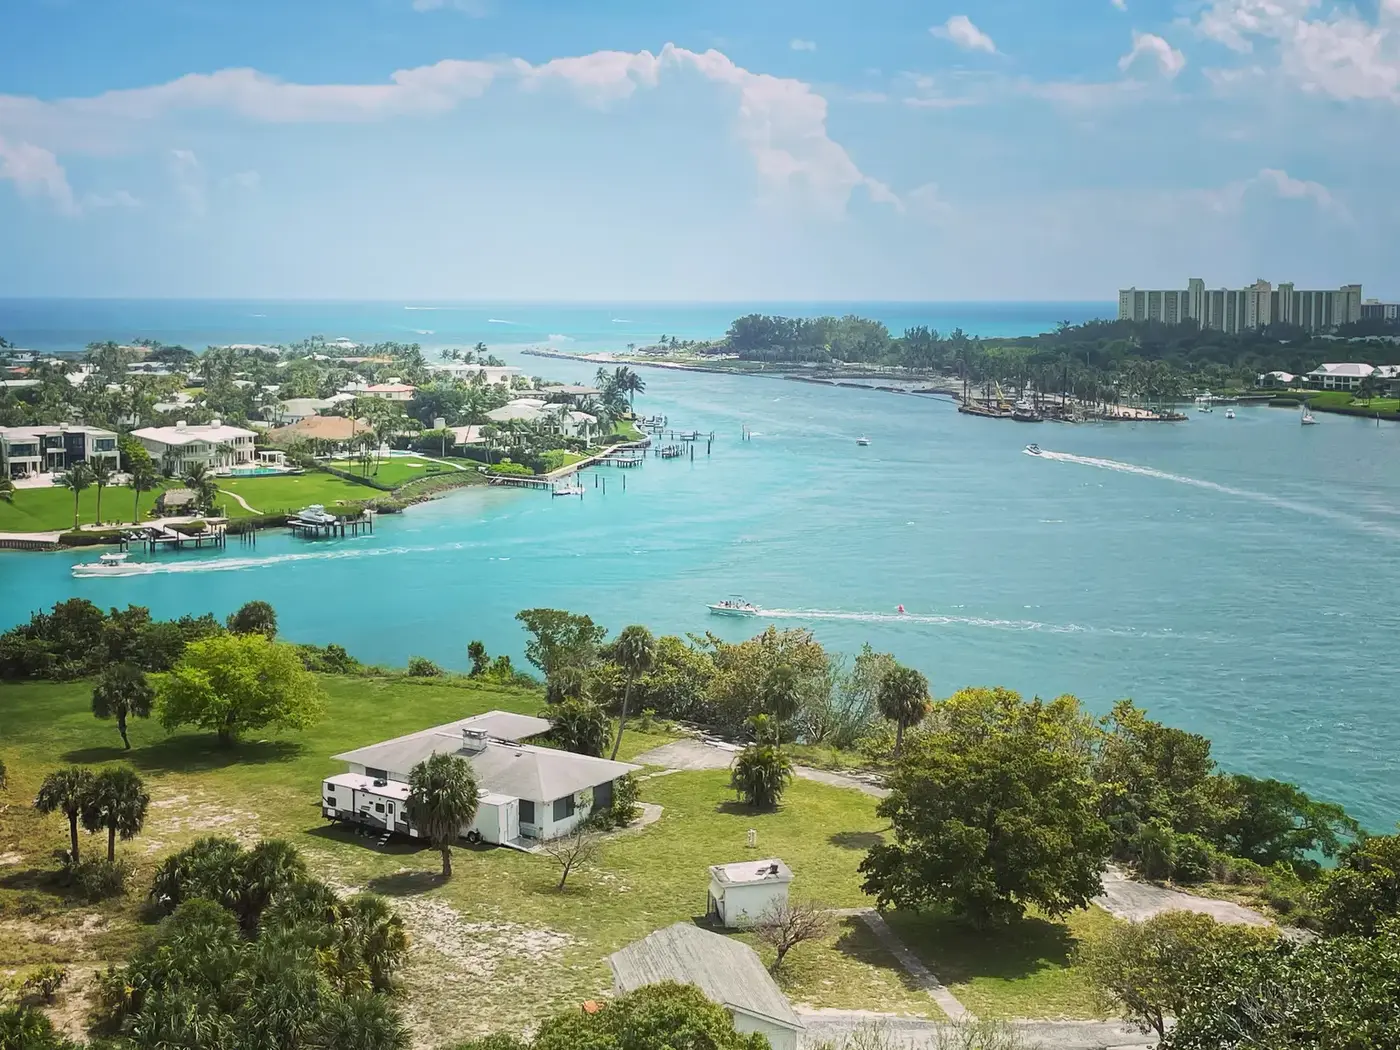
Jupiter housing and waterfront context
Utilities, maintenance and lifestyle spending
Treat this as a worksheet, not a page of averages. Every line is verified for the specific address, from prior bills, the providers, the inspection reports and your own choices.
| Cost category | Verify for the specific address |
|---|---|
| Electricity | Prior bills if available, system age, insulation, pool or spa equipment |
| Water, sewer or septic | Provider, current charges, service arrangement, septic maintenance history |
| Internet | Providers and service availability at the exact address |
| Landscaping, pool, pest | Existing contracts, lot size, equipment, and personal choices |
| Waterfront maintenance | Dock, seawall, lift, salt exposure, permits, and inspection findings |
| Vehicle and commuting | Actual routes, bridges, parking, tolls, fuel, and insurance choices |
| Optional recreation | Boat storage, dockage, club dues, dining, memberships, and other personal choices |
Water and sewer deserve one extra line. In the Jupiter area, water may come from the Town's utility or another provider, wastewater is handled by the Loxahatchee River District for much of the area, and some parcels rely on a well, a septic system or both. The seller's bills and the providers settle which applies.
Running the number before an offer
A property-specific checklist:
- Purchase price and financing terms from a licensed lender.
- A Property Appraiser estimate from the tax calculator, using your expected ownership and homestead scenario.
- Homeowners and flood quotes, in writing, for the exact property.
- Association, condominium, club and CDD documents, with any known assessments.
- Utility and maintenance records where available.
- Inspection findings, including roof, air conditioning, plumbing and electrical, and the seawall, dock and lift where they apply.
- Professional review of any tax, insurance, legal or lending question.
A full budget for one property is more useful than any citywide cost-of-living average. Build it for the address, then compare it with the same budget for another address, here or in a neighboring town. For how the trade-offs feel day to day, read what living in Jupiter is really like.
Community Guide
Neighborhoods, schools, prices, and lifestyle — all in one place.
Jupiter Market Trends
Live list-market data from the local MLS. It shows current conditions, not what one property costs to own.
Homes for Sale in Jupiter
Single-family homes $500k+, updated daily.
Next step
Have a Jupiter address in mind? Send it over and we will walk the checklist above against that property with you, line by line.
Frequently Asked Questions
What costs should I include when budgeting for a home in Jupiter?
The purchase financing, a property-tax estimate from the Palm Beach County Property Appraiser calculator for your ownership scenario, written homeowners and flood quotes for the exact property, association, condominium, club and any CDD obligations, utilities, maintenance including any seawall, dock or lift, and the inspection findings. Build it for one address rather than from a citywide average.
Can a listing's current property-tax bill predict my future bill?
Not reliably. The bill reflects the current owner's assessment and exemptions. The Palm Beach County Property Appraiser's tax calculator estimates a bill from the price you are contemplating and whether you intend to homestead; confirm the result and your eligibility with the Appraiser and a qualified tax professional.
How do Homestead Exemption and Save Our Homes work?
An owner who makes a property a permanent residence may be eligible for a homestead exemption that reduces its taxable value, with an application deadline of March 1. Once a homestead is established, Save Our Homes limits annual increases in assessed value under Florida law. Eligibility, amounts and timing are set by the state and county; the Florida Department of Revenue and the Property Appraiser are the sources.
Is flood coverage included in a standard homeowners policy?
Generally not. Flood coverage is usually a separate policy. Whether it is required depends on the property and the lender, and whether it is appropriate is a question for a licensed insurance professional. The FEMA Map Service Center gives the flood zone for the parcel.
What association and condo documents should I review before making an offer?
The current budget and fee schedule, what the dues include and exclude, reserve funding and any current or pending assessments, insurance responsibility and deductible allocation, the rules on rentals, pets, parking, exterior changes, docks, boats and generators, any club obligations the documents identify, and any CDD assessment on the parcel record.
When should I request insurance quotes for a Jupiter property?
During the inspection period, for the exact property, with the roof, wind-mitigation and four-point documentation the insurer asks for. Written quotes in hand before the contingency expires let you decide on real numbers rather than estimates.
Keep Reading
This article is provided by DO Homes Group at Premier Brokers International for informational purposes only and does not constitute legal, financial, tax, or investment advice. Market statistics, pricing, availability, HOA fees, and community details change frequently and may have changed since publication. School assignments, boundaries, and ratings may change — verify all school information directly with the appropriate school district, and consult official public safety resources for any crime data relevant to your search. Verify all details independently and consult the appropriate licensed professionals before making any real estate decision. DO Homes Group is committed to Equal Housing Opportunity and does not discriminate on the basis of race, color, religion, sex, handicap, familial status, or national origin.