
Westlake · Cost of Living
Cost of Living in Westlake, Florida
The purchase price is only part of the cost. Here's what shows up on a Westlake tax bill and in the HOA documents, and how to price one specific address.
By John OliverUpdated
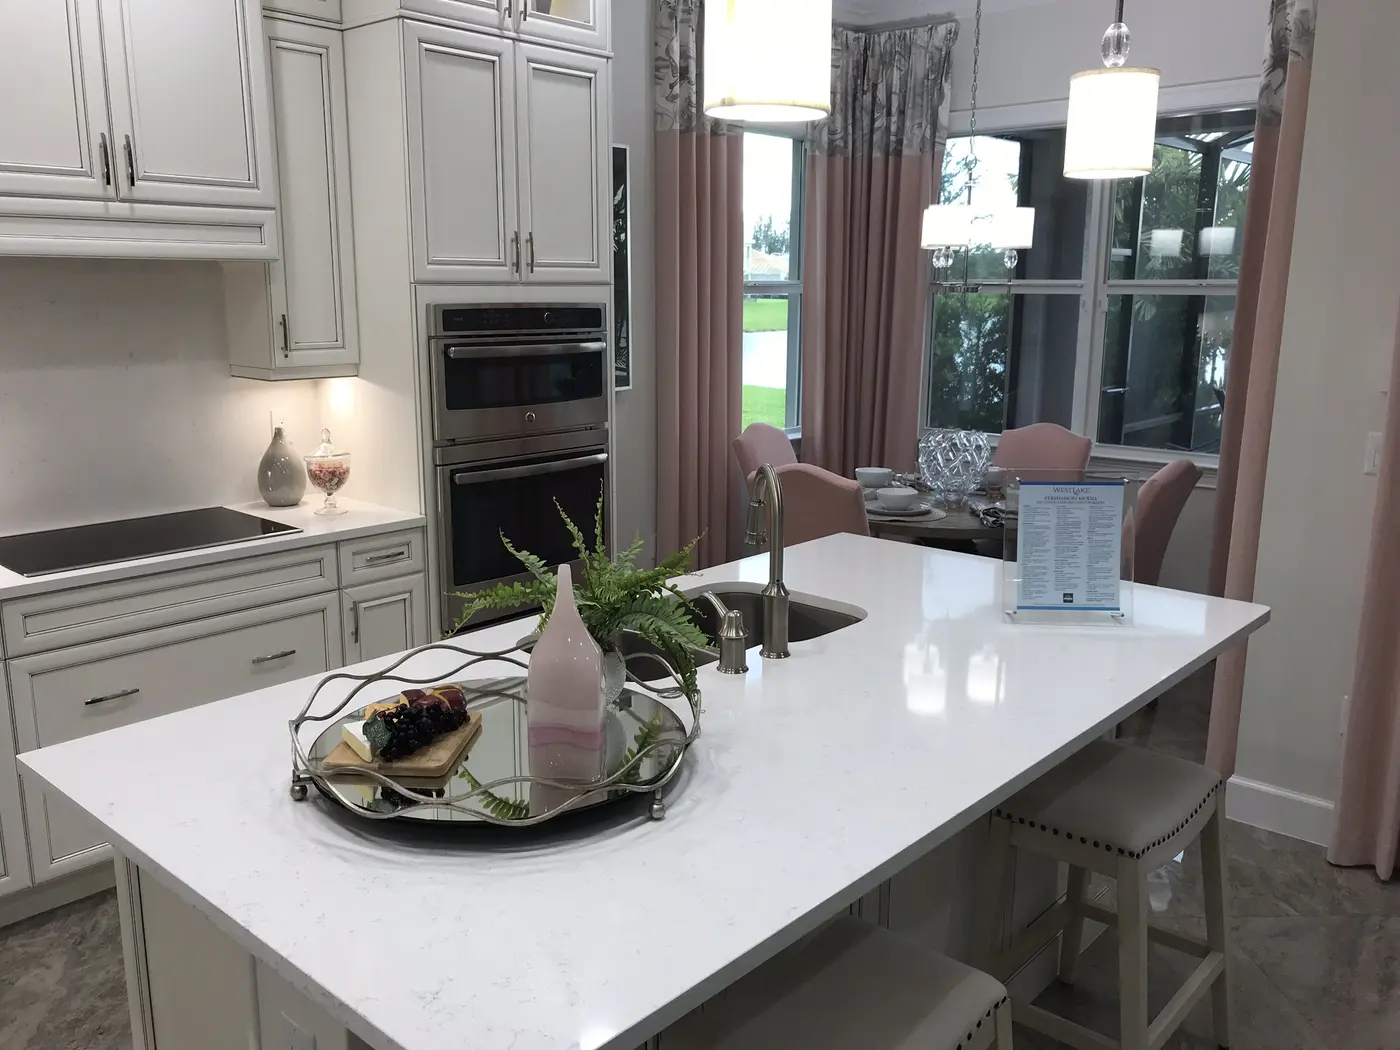
A staged kitchen in a Minto model home in Westlake, photographed in 2018. Finishes, options and pricing vary by builder, plan and phase.
What a Westlake home costs to own depends on the address. The purchase price is one part. The rest is the property tax bill and the assessments on it, association dues, insurance, utilities and the driving your routine requires. None of these is the same for every home, so this guide explains each one and how to get the real figures before you commit.
We don't publish price ranges, fee averages or appreciation figures here. Ask the builders and your agent for current pricing and recent sales of comparable homes.
Recent closed-sale medians have moved modestly in some Westlake segments. Because the number of sales can be small and the mix of new construction and resale homes changes, a single month is not a reliable citywide price trend. Request current comparable closed sales for the specific home type and neighborhood.
What actually moves the monthly number
Two Westlake homes at the same price can cost different amounts to own. These are the items that make the difference.
The property tax bill
City, county, school and other millage, plus non-ad valorem assessments from the Seminole Improvement District and the city's residential solid waste assessment. The amounts depend on the parcel.
Reassessment and new-construction timing
A change in ownership can remove the seller's exemptions and assessment limits, and a new home's first bill may reflect only the land or a partly finished house. Don't budget from the seller's bill or the first one you see.
Association dues
Some homes may have a master association, a neighborhood association, or both. Verify every association tied to the specific property, and its fees, reserves and rules.
Insurance
Homeowners, wind and flood quotes depend on the property, its features and its flood zone. Get real quotes for the address.
Utilities and driving
SID water, wastewater and reuse water, FPL electricity, internet, and the miles you drive for work, errands and appointments.
In this guide
What's on a Westlake property tax bill
A Westlake tax bill has two kinds of charges, both collected by the Palm Beach County Tax Collector.
| Part of the bill | What it is | Where to check it |
|---|---|---|
| Ad valorem taxes | Taxes based on assessed value: the county, the school district, the City of Westlake and other taxing authorities each set a millage rate. | The Property Appraiser record and the annual notice of proposed taxes for the parcel. |
| Seminole Improvement District (SID) assessments | Special assessments and/or taxes for the district that operates and maintains Westlake's water, sewer, drainage, roads and related infrastructure. The city's lien search guidance says they appear on the tax bill as non-ad valorem assessments. | The current tax bill, and a property assessment and lien search. |
| Residential solid waste assessment | The city collects the cost of residential trash and recycling service as a non-ad valorem special assessment on the tax bill. | The current tax bill and the city's solid waste pages. |
How the SID fits in, and why this isn't a typical CDD
Many Florida master-planned communities finance infrastructure through a community development district that issues bonds repaid by homeowners. The City of Westlake's history describes a different arrangement: the developer paid for the roads, landscaping, water, sewer, stormwater and reuse-water systems and turned them over to the SID to operate and maintain.
That doesn't make the SID line on a tax bill zero, and SID charges aren't a "CDD fee." Owners still pay SID assessments, and the charges aren't necessarily identical from one home to the next. For the exact parcel, confirm the non-ad valorem line items on the current bill, any remaining assessment obligations, how they're handled at payoff or transfer, and the lien information, through a property assessment and lien search (see the SID's assessment and lien search guidelines and its Who to Call page). Ask in writing about any other assessment or obligation tied to the property.
The reassessment and new-construction timing
The seller's tax figure isn't yours. Florida limits how much the assessed value of a homestead can rise each year (Save Our Homes), and non-homestead property has its own limit. A change in ownership can remove the prior owner's exemptions and assessment limitations, and the Property Appraiser may reassess the home toward its just (market) value, so a seller's bill can understate what you'll pay. Estimate your taxes using your intended purchase price, your likely ownership date and whether you'll be eligible for homestead. The Property Appraiser's residential page and FAQ explain how property is valued, and the Tax Collector explains the bill.
New construction has a timing wrinkle. Property is valued based on its condition as of January 1. Depending on how far along a house is on that date, the next bill may reflect land value or a partially completed improvement, and a later bill may reflect the finished home. Ask what a fully assessed bill on a comparable finished home looks like rather than budgeting from the first bill.
Homestead exemption applies only to a permanent residence you own and occupy on January 1, with a filing deadline of March 1; see the Property Appraiser's homestead page. If you're moving from another Florida homestead, ask the Property Appraiser about portability.
Association dues
Some homes may have a master association, a neighborhood association, or both; verify every association tied to the specific property. Before you commit, get:
- The current fee for every association the home belongs to, and how often each is billed.
- The budgets, reserve information where available, and any pending or planned special assessments.
- Application, transfer and capital contribution fees due at closing.
- The rules, including rental and pet restrictions, parking, exterior changes and amenity access.
- The estoppel certificate, which states what's owed as of closing.
Insurance
Premiums depend on the specific property: its construction and roof, how its windows and doors are protected, its wind mitigation features, its flood zone and the coverage you choose. Ask whether a wind mitigation inspection applies, and get real quotes for the address before you commit.
A newer home isn't necessarily cheaper to insure; the quote for the specific property is what counts. Flood coverage is generally separate from a standard homeowners policy. Evaluate it for the property, considering the flood zone, elevation, your lender's requirements, the coverage you choose and the deductible; see the state's flood insurance information and its homeowners insurance overview.
Utilities
- Water, wastewater and reuse water come from the SID. Starting service involves an online application, a start-up fee and a deposit; see the SID's utility FAQ for current amounts.
- Electricity is from FPL; confirm service for the address. Usage depends on the home and the household, so ask the seller for recent bills if they're available rather than relying on an average.
- Internet options and prices vary by address, so check providers for the specific home.
Our Westlake local guide covers setting up each service.
Everyday costs
- Driving. Westlake is in western Palm Beach County. Count the real mileage for the routes your own routine requires: work, errands, medical care and dining.
- Groceries and errands. A Publix-anchored shopping center opened on Seminole Pratt Whitney Road in 2023. Other retail has been approved, and approval isn't the same as open; the city lists approvals on its development orders page.
- Maintenance. Even a new home needs lawn, pest control, pool service if there's a pool, and filters and routine upkeep. Some of this may be covered by an association; check what yours includes.
New construction or resale: what changes
| Buying new from a builder | Buying a resale | |
|---|---|---|
| Price | Base price, lot premium, structural options, design selections, lender incentives and closing costs can all vary. | The negotiated purchase price, which can be affected by inspection findings, condition and seller concessions. |
| Warranty | Verify the builder's specific warranty documents; don't assume coverage. | Any remaining builder warranty, if it transfers; verify the terms. |
| Taxes | The first bill may reflect land or a partly finished house; budget for a fully assessed bill. | The seller's exemptions and assessment limitations don't automatically transfer to you. |
| Inspection | Arrange an independent inspection of a completed or near-complete home. | Arrange an independent inspection, including the roof, systems and maintenance history. |
Running your own number
- Get the current tax bill for the parcel, and estimate your own bill using your intended purchase price, likely ownership date and homestead eligibility, without the seller's exemptions.
- For new construction, ask what a fully assessed bill on a comparable finished home looks like.
- Confirm the SID and solid waste line items on the bill, any remaining assessment obligations, and the lien information, through a property assessment and lien search requested by your title company.
- Get every association's fee, budget, rules, reserve information, closing fees and pending assessments, and the estoppel certificate.
- Get homeowners, wind and flood insurance quotes for the address.
- Add utilities, maintenance and driving.
- Add it up as a monthly figure, together with your mortgage payment, and check it against the actual closing disclosures before you commit.
This is a budgeting checklist, not legal, tax, insurance or financial advice. Confirm each item with the Property Appraiser, the Tax Collector, the associations, a licensed insurance agent and your lender.
The bottom line
Westlake's costs can be reviewed in advance: the tax bill and its assessments, the association documents, insurance quotes, utility setup and the closing disclosures are all available for a specific address. Collect them before you compare homes, and compare the monthly total, not the sticker price.
For more, read what living in Westlake is really like, the neighborhood and home-collection guide, the pros and cons and Westlake vs nearby cities.
Community Guide
Neighborhoods, schools, prices, and lifestyle — all in one place.
Free Relocation Decision Guide
Palm Beach County or the Treasure Coast?
A side-by-side comparison of 14 areas we actually work in — from Boca Raton to Port St. Lucie — across 12 things that decide where you should live.
Thinking about Westlake?
We're local experts — let's find the right home for your move.
Homes for Sale in Westlake
Single-family homes $500k+, updated daily.
Frequently Asked Questions
What is on a Westlake property tax bill?
Ad valorem taxes from the county, school district, City of Westlake and other taxing authorities, plus non-ad valorem assessments. Those include Seminole Improvement District (SID) assessments and the city's residential solid waste assessment. The amounts depend on the parcel, so check the current bill for the specific address.
Does Westlake have a CDD?
Westlake's infrastructure is operated and maintained by the Seminole Improvement District (SID), a special district whose boundaries match the city's, not a typical community development district. According to the city, the developer paid for the roads, water, sewer, stormwater and reuse-water systems and turned them over to the SID. Owners still pay SID assessments, which appear on the tax bill as non-ad valorem charges. Check the tax bill and a parcel-specific assessment and lien search for the exact home.
Why might taxes change after purchase?
A change in ownership can remove the seller's exemptions and assessment limitations, and the Property Appraiser may reassess the home toward its market value. Property is also valued based on its condition on January 1, so a new home's first bill may reflect land or a partly finished house. Estimate your taxes using your purchase price, ownership date and homestead eligibility.
What HOA fees should I expect in Westlake?
It varies. Some homes may have a master association, a neighborhood association, or both. Ask for every association's current fee, budget, rules, reserve information, closing fees and pending assessments, and the estoppel certificate, for the exact address.
Is insurance cheaper on a newer home?
Not necessarily. Premiums reflect the specific home's construction, roof, opening protection, wind mitigation features, flood exposure and the coverage and deductibles chosen. Flood coverage is generally separate from a homeowners policy. Get property-specific quotes before you rely on any savings.
What should I review before buying?
The current tax bill and your own estimate; the SID and solid waste line items and a parcel-specific assessment and lien search; every association's fees, rules, budget and estoppel certificate; homeowners, wind and flood insurance quotes; utility setup; and the actual closing figures. This is a budgeting checklist, not legal, tax or financial advice.
Keep Reading
This article is provided by DO Homes Group at Premier Brokers International for informational purposes only and does not constitute legal, financial, tax, or investment advice. Market statistics, pricing, availability, HOA fees, and community details change frequently and may have changed since publication. School assignments, boundaries, and ratings may change — verify all school information directly with the appropriate school district, and consult official public safety resources for any crime data relevant to your search. Verify all details independently and consult the appropriate licensed professionals before making any real estate decision. DO Homes Group is committed to Equal Housing Opportunity and does not discriminate on the basis of race, color, religion, sex, handicap, familial status, or national origin.